CHAPTER 3 · Learning to Love Your Corporate Culture
What a trading floor teaches without saying
Identify the behaviours a firm actually rewards.
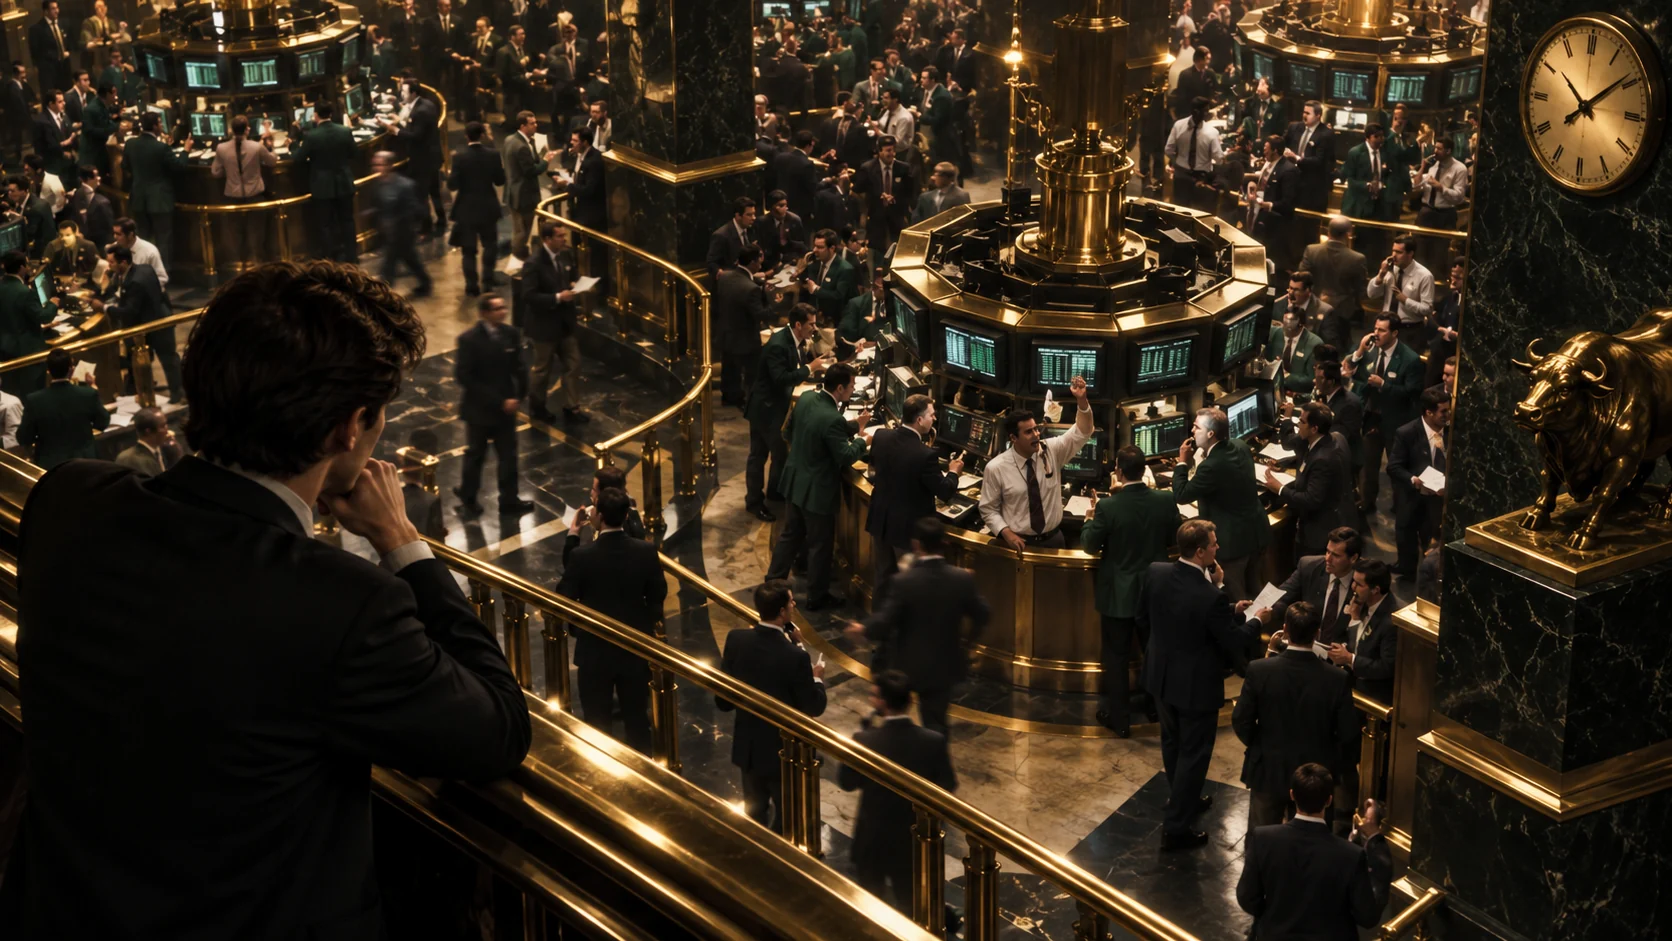
Michael Lewis, Liar’s Poker · Chapter 3. Original paraphrase and analysis; not the book text.
The idea beneath the story
A training programme teaches more than product definitions. In Lewis’s account, the trainees learn where to sit, whom to impress and which departments count as desirable. The classroom develops its own hierarchy. The trading floor supplies a second curriculum through ridicule, patronage and access to senior people. Lewis describes the process with satire; the learning question is how an organisation’s daily rewards can contradict its formal statements.
For someone studying a listed company, culture is not an ornamental paragraph in an annual report. It affects which information reaches decision-makers. If reporting a problem damages a person’s status while generating revenue brings immediate praise, the organisation creates a reason to postpone bad news. The crucial distinction is between knowing a policy and being able to use it when a profitable colleague objects. A written rule can be excellent and still fail at the point of conflict.
This does not mean an informal culture is always harmful. Shared language and trust can help people coordinate quickly. An experienced team may recognise a developing problem before a formal dashboard does. But belonging becomes dangerous when it substitutes for testing. A new colleague may notice an inconsistency precisely because they have not yet learned to ignore it. If the price of membership is silence, the firm discards a useful source of information.
Hypothetical worked example: a dealing desk earns £2 million in a quarter. A junior employee notices that a valuation input is stale and estimates that correcting it would reduce reported profit by £300,000. The desk head’s bonus depends on crossing a £1.8 million threshold. The corrected figure, £1.7 million, falls below it. This creates a conflict even if no one has yet acted improperly. A useful control assigns valuation review outside the desk and records the correction before remuneration is finalised. Telling the junior employee to be brave leaves the conflict unresolved.
The equity connection is earnings quality. A shareholder normally sees the published number after many internal choices have been made. Some choices involve judgement rather than mechanical calculation: provisions, useful lives, impairment assumptions and revenue recognition. You cannot infer a misstatement merely from a performance target. You can ask whether independent review has authority, whether concerns recur and whether the board receives the same information as the people producing the number.
Watch how a company describes a failure. Does it identify the sequence, the control that did not work and the person or role responsible for improving it? Or does it attribute everything to one careless employee while leaving the incentive structure untouched? Individual accountability matters, but a repeated pattern may indicate a design problem. Replacing a person without changing the process can create a fresh opportunity for the same error.
The Knight Capital comparison involves software, not Lewis’s training room. Its relevance is the distance between a control existing and a control limiting actual exposure. A system can produce messages without ensuring that the right person interprets them in time. A checklist can confirm that components are present without testing what happens when they interact badly. The stock-market lesson is to inspect the organisation around the technology, rather than assuming technology removes human incentives.
There are limits to outside analysis. Investors rarely observe the whole internal culture, and isolated anecdotes can mislead. Treat employee accounts, disclosed incidents and governance arrangements as evidence to triangulate, not a personality test. The best question is specific: which bad news can travel upward, through which route, and with what practical consequence? A culture that can correct itself should leave a trace in decisions, not only in slogans.
Knight Capital: when orders outrun controls
Knight’s later failure helps test whether escalation and limits work under pressure. This is an organisational comparison, not a claim that the two firms shared identical cultures. This case is shared with related chapters.
Documented sequence. On 1 August 2012, a faulty code deployment activated defective functionality in Knight Capital’s equity order router. The SEC described millions of erroneous orders and a loss exceeding $460 million. It found weaknesses in deployment, exposure controls and incident procedures. In 2013, Knight agreed to a $12 million settlement without admitting or denying the findings. The episode concerns operational exposure in equity markets, rather than an investment forecast that happened to be wrong.
SEC · Knight Capital market-access enforcement, 2013 · Checked 10 October 2026
Original analysis: a chain, not a typo. A software error becomes a financial disaster when it reaches a live market, generates exposure and continues long enough to overwhelm the firm’s capacity. A useful explanation therefore includes deployment, detection, authority and containment. Focusing only on the defective code leaves unanswered why the resulting orders were allowed to accumulate and why the response did not stop the financial consequence sooner.
Think about the difference between a message and an effective alert. A message is information emitted by a system. An effective alert has an owner, a meaning, a deadline and an action. If the recipient cannot tell whether it indicates a harmless anomaly or an accumulating position, more messages may simply increase noise. This is an original design inference, not a claim that the precise communication choices of every employee are known from the source.
Hypothetical worked example. A system mistakenly buys £100,000 of stock each second. In one minute it has acquired £6 million; in ten minutes, £60 million, assuming the orders execute at those amounts. A person who takes five minutes to understand the issue may be conscientious and still far too slow for the system’s risk-creation rate. A pre-trade exposure cap or automatic stop can operate on a different timescale. Real controls also need to handle false positives and safe recovery.
The shareholder’s question is whether the business can create obligations faster than its governance can observe them. This applies beyond high-frequency trading. Credit approvals, payment systems and automated pricing can all scale a mistake. Growth in throughput is not automatically growth in resilience. If management celebrates transaction speed, ask how quickly it can detect a discrepancy and how much capital could be consumed before an authorised intervention.
The connection to Lewis’s training culture is specific: policies and expertise require an operating environment that turns them into action. The connection to his final chapter is different: commitments can accumulate before people fully understand their economic effect. These comparisons do not make software failure equivalent to an underwriting loss. They supply two separate questions about a documented later event.
A common misunderstanding is that more technology automatically means less human risk. Automation removes some manual errors and introduces new dependencies. Another is that one employee’s mistake fully explains the event. Individual mistakes are part of the chain; robust systems assume that mistakes can occur and limit their reach. The relevant standard is not perfection but bounded consequences.
Takeaway. A risk limit should be able to prevent or contain the unwanted position, not merely report it after the fact. Ask what is measured, where the measurement occurs, who can halt activity and how the system is restored safely. A successful test should include an abnormal path, because the ordinary path is precisely where a fragile design can look most convincing.
Workshop: audit an equity claim
Begin with a claim that could be wrong. “This is a great company” is too elastic to investigate because almost any observation can be accommodated inside it. “The company can improve its operating margin without increasing credit risk or deferring necessary expenditure” is more useful. It identifies an outcome and two possible ways the appearance of improvement could mislead. A reader can now ask which disclosures bear on each part. This discipline converts the social question of whether management seems impressive into an economic question that can be checked.
Build an evidence ledger with three columns: observation, interpretation and unresolved question. An observation might be that revenue rose while cash collected from customers did not rise proportionately. One interpretation is that customers are taking longer to pay. Another is that the sales mix changed or the period ended at an unusual point in the billing cycle. The unresolved question is what explains the difference. Recording alternatives prevents the first plausible story from becoming a fact simply because it was written down confidently. The ledger is a research aid, not an accusation of misconduct.
Next identify the denominator. If a company announces that ninety per cent of a selected customer group renewed, ask who was eligible for that group and who was excluded. If a fund highlights its ten best investments, ask how many investments it made altogether. If a manager reports a successful product launch, ask how much capital and failed experimentation preceded it. Denominators make stories comparable. They also expose a limitation: two apparently similar ratios may use different definitions. Before comparing companies, reconcile what each number includes and the period over which it is measured.
Consider a hypothetical software company with £20 million of revenue and £4 million of operating profit. It spends £3 million on development, of which £2 million is treated as an asset rather than an immediate expense. The appropriate accounting depends on facts and applicable standards; the example does not decide whether capitalisation is permitted. For analysis, however, the cash has left the business either way. An investor should examine the useful life, later amortisation, impairment risk and whether the expenditure must recur. A reported margin without that cash context can make economic reinvestment look cheaper than it is.
Now map decision rights. A board committee, finance team and external adviser may all appear in a governance description, but their practical powers differ. Who can require a revised number before publication? Who receives contrary evidence? Who sets the assumptions used in a valuation? Who decides the compensation linked to the result? Formal independence is one input; access to information and authority to act are others. The aim is not to infer secret behaviour from an organisation chart. It is to identify which checks would need to operate for the published control story to be credible.
The timing of rewards matters. Suppose a salesperson receives a bonus when a contract is signed, while credit losses emerge eighteen months later in a central account. The arrangement can encourage volume even if nobody intends to harm the firm. A better measurement might track collections, cancellations and realised margins over time. Yet delayed compensation is not a universal cure: employees may have limited control over later macroeconomic changes. A thoughtful design separates controllable decisions from broad market outcomes while retaining responsibility for foreseeable consequences. Simple slogans about paying for performance conceal this difficult attribution problem.
Look for counterevidence that would change the conclusion. If you suspect that rising profit comes from underinvestment, stable service quality and independently supported maintenance spending may weaken the suspicion. If you think customer loyalty is deteriorating, cohort data showing resilient retention may matter more than a loud complaint. The point is to state the test before the result arrives. Otherwise, every favourable number can become proof and every unfavourable one an exception. A falsifiable thesis is not a promise that one metric will settle everything; it is a commitment to let evidence constrain the story.
A strong comparison also considers the business model. A subscription company, an insurer and a manufacturer turn revenue into cash on different schedules. Applying the same superficial rule to all three can produce false alarms. Use accounting relationships to generate questions, then investigate the relevant contracts and operating cycle. Where the necessary disclosure is absent, say so. The absence of information may justify a lower degree of confidence or a decision to stop researching. It does not justify filling the gap with a precise estimate presented as known fact.
Keep a decision journal that records what was knowable at the time. Include the initial claim, sources, assumptions, competing explanations and the next event that could clarify matters. If you later revise the view, append the revision instead of silently replacing the original. This protects against hindsight and makes learning possible. A profitable investment can still reveal weak reasoning, while an unprofitable one can contain a well-formed thesis undermined by genuinely new information. The journal should help distinguish those situations without becoming a device for excusing every mistake.
Finally, separate analysis from action. Discovering a credible business does not establish that its shares are attractively priced, suitable for a particular person or safe under leverage. Discovering a conflict does not establish that the opposite trade is profitable. The output of this workshop is a clearer evidence record, not a buy or sell instruction. Its practical value is the ability to explain why you place weight on a claim, what you have not established and what would make you change your mind. That is a more durable outcome than borrowing confidence from a prestigious speaker.
A final hypothetical check concerns selective comparison. Management compares its current margin with a rival’s recession-year margin and calls the difference evidence of superior execution. The subtraction may be correct, but the comparison mixes environments. A stronger review compares like periods, checks product mix and asks whether the firms recognise costs similarly. If those conditions cannot be reconciled, describe the result as suggestive rather than decisive. The objective is not to find a comparison that flatters a preferred view. It is to learn which differences remain after obvious alternative explanations have been considered. This same discipline applies to a fund’s chosen benchmark, a salesperson’s chosen customer examples and a division’s preferred allocation of overhead. Choosing the yardstick is part of making the argument, so the yardstick deserves as much scrutiny as the result displayed beside it.
Decision exercise (hypothetical)
A profitable desk asks to delay a valuation correction until after bonus decisions. What should happen?
- Wait to protect morale
Morale cannot justify knowingly postponing an accounting correction.
- Let the desk approve its own exception
That leaves the conflict with the people benefiting from it.
- Obtain independent review and record the correction promptly
Yes. Independence and timely evidence address the conflict directly.
Recall and self-check
What is an informal curriculum?
The behaviours people learn from rewards, access and sanctions.
Does a written policy prove a control works?
No. Test who can invoke it, especially against a profitable activity.
Reflection
Which piece of evidence would distinguish a slogan from a functioning control?
Look for a recorded intervention, an independent decision and a changed outcome.
Open interactive chapter & notes